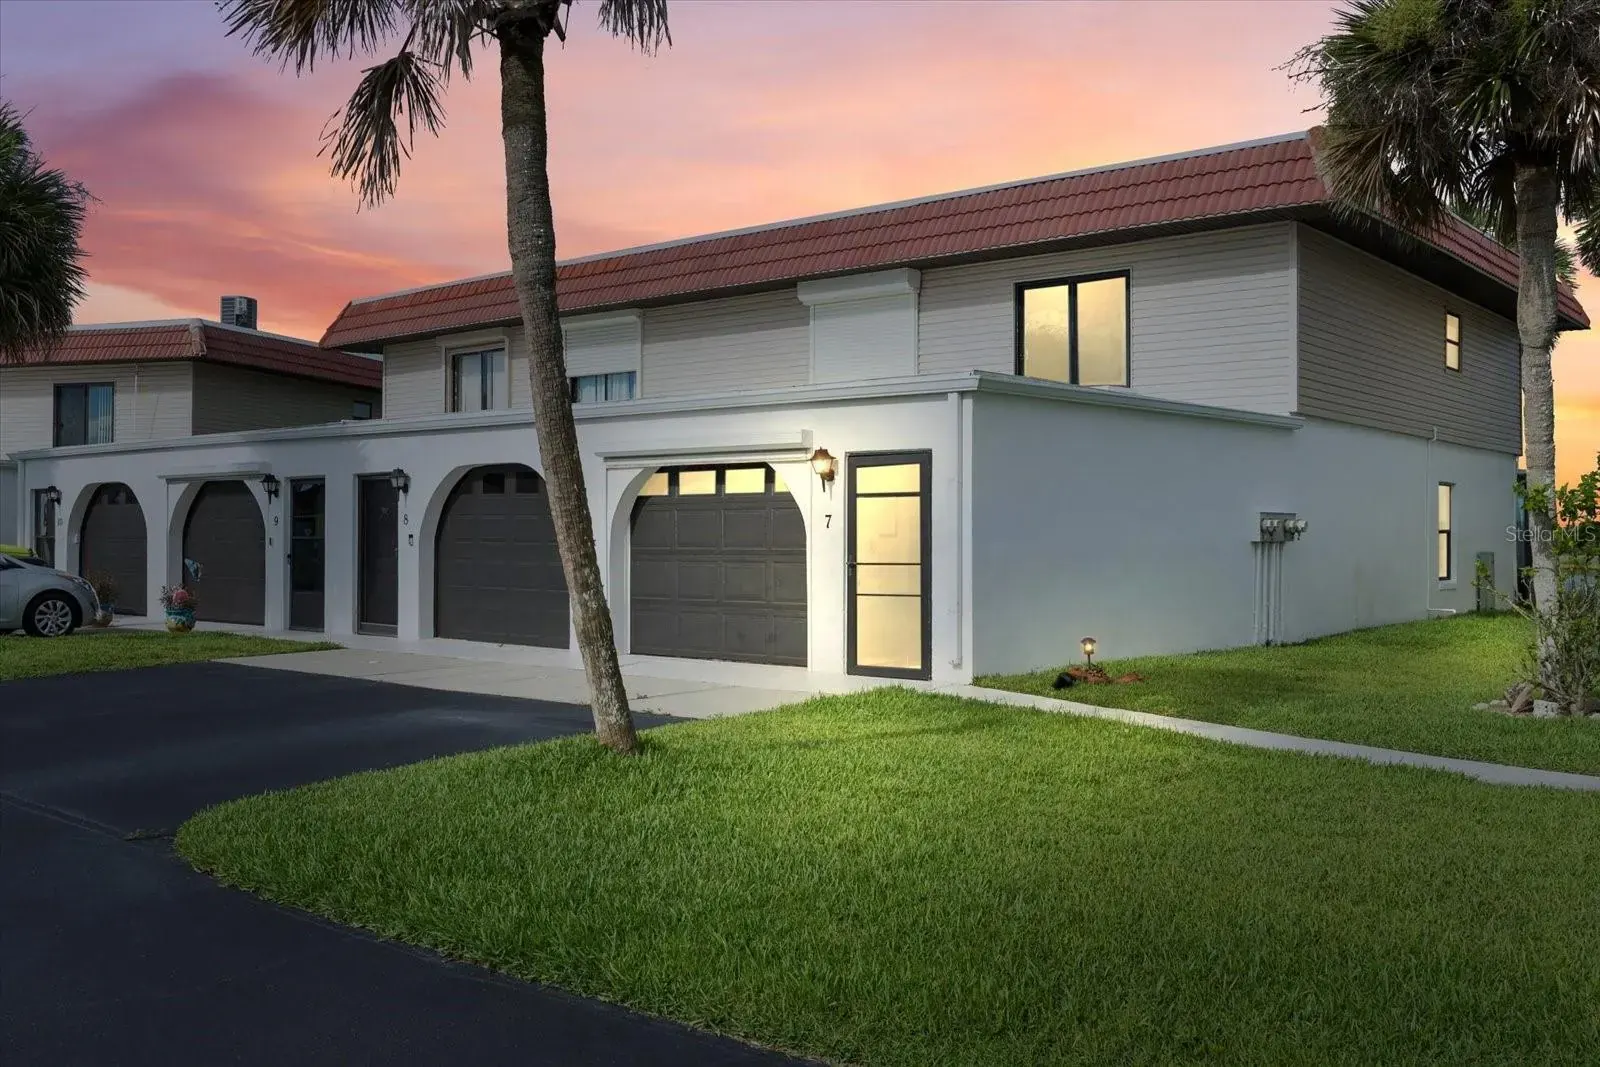
Buying a home in Florida works a lot like buying anywhere else, with a handful of Florida-specific steps that surprise people: insurance inspections, flood disclosures, CDDs, the homestead exemption and how closing costs get split. Here's the process I walk my buyers through in Palm Coast and Flagler County, from the first meeting to the keys, updated for 2026.
1. Get pre-approved and know your cash
Start with a full pre-approval from a local lender, not a quick online prequalification. You'll provide pay stubs, W-2s or tax returns, bank statements and permission to pull credit. A real pre-approval tells you what you can buy and makes your offer stronger. I'm happy to recommend lenders who close on time here.
- Down payment: some conventional loans allow 3% down, FHA starts at 3.5%, and VA and USDA loans can be zero down for eligible buyers.
- Closing costs: when you're financing, I tell buyers to budget about 3% of the price for closing costs, plus inspections, the appraisal and a survey.
- Your payment: rates move every week. Try different prices and down payments in my mortgage calculator, and my monthly market report tracks where rates are heading.
2. Sign a written buyer agreement before you tour
Since August 17, 2024, MLS rules have required a written agreement between a buyer and the agent working with them before touring a home, and that includes a live virtual tour. The agreement states how and how much the agent is paid, and it has to say that fees are negotiable. You can also ask the seller to cover some or all of it as part of your offer. I go over every line before you sign, so there are no surprises later.
3. Shop and tour homes
Most of my buyers see 10 to 15 homes over three or four trips. I'll set up a search on Home Search that sends you the right homes the day they hit the market, schedule the tours, and give you an honest read on price, condition and resale. The right home might show up on day one or on trip four. Either is normal.
4. Make an offer and negotiate seller concessions
Once you find the one, we'll review recent sales, then write an offer that covers price, deposit, closing date, inspection period and financing terms. In today's market, flexible terms can matter as much as price.
Seller concessions are credits from the seller toward your closing costs or a rate buydown. They don't put cash in your pocket, but they lower what you bring to closing or what you pay each month. Sometimes a credit helps you more than a lower price, especially if cash to close is tight. Each loan program caps how much a seller can contribute, so we'll check the limit with your lender before we write the number.
5. Under contract: deposit and deadlines
Your escrow deposit goes to the title company or closing attorney. From there I track every deadline and keep the lender, the title company and the other agent moving:
- The inspection period, usually 7 to 15 days here
- Loan approval and appraisal deadlines
- Title search and survey
- Closing, usually 30 to 45 days from an accepted offer
One warning I give everyone. Never wire money based on emailed instructions without calling the title company at a phone number you already know. Wire fraud targets home buyers.
6. Inspections, Florida style
Most buyers here order a package: a general home inspection, a WDO (termite) inspection, a 4-point inspection and a wind mitigation inspection.
- 4-point: covers the roof, electrical, plumbing and AC. Insurers often ask for one on older homes before they'll write a policy.
- Wind mitigation: documents roof straps, roof shape, impact windows and shutters, which earn credits on the wind part of your premium.
- Roof age: Florida law bars an insurer from refusing to write or renew a policy solely because the roof is less than 15 years old. An older roof can still qualify if an inspection shows at least five years of life left.
If the reports turn up big issues, we can negotiate repairs or a credit, or walk away within the inspection period. The state's My Safe Florida Home program offers free wind mitigation inspections and grants of up to $10,000 for eligible upgrades when funding is available.
7. Insurance and flood
Your lender needs a homeowners policy in place before closing, so start quotes as soon as you have the inspection reports. Homeowners policies don't cover flood, which is a separate policy.
- Look up the flood zone on FEMA's Flood Map Service Center. In a high-risk zone, a federally backed mortgage requires flood insurance.
- Read the seller's flood disclosure. Florida law requires sellers to give you a flood disclosure at or before the time you sign the contract. Since October 1, 2025, it covers whether the seller knows of flooding that damaged the home while they owned it, any flood insurance claims, and any flood-damage assistance they received, from FEMA or anyone else.
- Citizens policies: if your home insurance ends up with Citizens, the state-backed insurer, flood coverage is already required in high-risk zones and on homes with a replacement cost of $400,000 or more. Starting January 1, 2027, it's required on every Citizens home policy that includes wind coverage.
My flood zone guide shows how to read a flood map for any Palm Coast address.
8. HOAs, CDDs and the estoppel letter
CDDs. A community development district is a special district that pays for roads, water lines, amenities and similar improvements, and its assessment shows up on your property tax bill. Florida law requires a bold disclosure right above your signature when a developer first sells a lot or home in a CDD. In Flagler County, the Property Appraiser's 2026 tax district list includes CDDs such as Grand Haven, Palm Coast Park, Town Center, Hammock Dunes and Deer Run. Ask how much of the yearly charge is debt payment and when that debt pays off. My CDD vs. HOA guide explains both.
HOAs. Read the rules, the budget and any approval requirements before your inspection period ends. Near closing, the title company orders an estoppel certificate that shows what the seller owes the association. Florida law gives the association 10 business days to issue it and caps the fee, and your contract says who pays it.
9. Title insurance, doc stamps and closing costs
The owner's title policy protects you if a problem with the title shows up after closing. In Flagler County, the custom is that the seller pays for the owner's policy and usually chooses the title company. It's negotiable, and the contract spells it out. If you're financing, the lender's policy is your cost. Florida sets title insurance premiums by state rule, so what differs between title companies is mostly their closing fees.
Florida also charges documentary stamp tax. The deed is taxed at $0.70 per $100 of the price, and here the seller customarily pays it. If you take out a mortgage, you pay $0.35 per $100 of the loan in doc stamps plus a 0.2% intangible tax.
| Example: $400,000 price, $320,000 loan | Amount | Usually paid by |
|---|---|---|
| Doc stamps on the deed | $2,800 | Seller |
| Doc stamps on the mortgage note | $1,120 | Buyer |
| Intangible tax on the mortgage | $640 | Buyer |
Property taxes and HOA dues are prorated between you and the seller at closing. For the full list of what buyers pay here, see my hidden costs of buying in Flagler County.
10. Appraisal and clear to close
The lender's appraisal checks that the value supports your price. If it comes in at or above the contract price, we keep moving. If it comes in low, we can renegotiate, you can cover the gap, or we can use the contract's protections to move on.
Once your loan is approved, the lender sends your Closing Disclosure. Federal rules require it at least three business days before closing, so you have time to compare it with your loan estimate. Send your lender any last pay stubs, bank statements and your insurance declarations page quickly so nothing slips.
11. Closing day and the steps after
You'll sign at the title company or the closing attorney's office. Bring a valid ID and your verified funds. In most deals you get the keys at closing once the transaction funds.
Then put these on your calendar:
- Homestead exemption. If the home is your primary residence, you must own and live in it on January 1 and file by March 1. For 2026 it takes up to $51,411 off your taxable value. My homestead guide walks through filing in Bunnell.
- Your taxes will reset. The seller's Save Our Homes cap ends with the sale, and the home is reassessed at market value the next January 1. Don't budget off the seller's tax bill. Starting February 1, 2027, Florida's 2026 tax package requires online listing sites to show buyers an estimated tax instead of the current owner's bill.
- Amendment 3. It's on the November 3, 2026 ballot and needs 60% to pass. If it passes, people who are permanent Florida residents by December 31, 2026 would qualify for a much larger homestead exemption on non-school taxes starting in 2027, while new residents after that would wait until their fifth year. Read my Amendment 3 breakdown.
- Utilities. Set up electric, water and internet before closing day. My utility bill guide lists the providers and current rates.
First-time buyer programs
The Florida Housing Finance Corporation offers first mortgages through participating lenders, with a 640 minimum credit score and a homebuyer education course. Its current down payment and closing cost programs:
- Florida Assist: up to $10,000 as a 0%, deferred second mortgage. It isn't forgiven, and it's due when you sell, refinance or move out.
- HFA Preferred and HFA Advantage PLUS: 3%, 4% or 5% of the loan amount as a second mortgage forgiven at 20% a year over five years, with conventional HFA first mortgages.
- Florida Homeownership Loan Program: $12,500 as a 3%, 30-year second mortgage with a monthly payment.
- Hometown Heroes: up to 5% of the first mortgage ($10,000 to $35,000) as a 0%, deferred second mortgage for income-qualified first-time buyers who work full time for Florida employers in fields like health care, schools, first responders and public safety, courts and child care, plus military service members and veterans working full time for Florida employers. The last round's money was fully committed on February 20, 2026. The 2026-27 state budget added $50 million, and Florida Housing posted its 2026 program rules in July. Ask a participating lender whether funds are still available before you count on it.
Flagler County also runs its own purchase assistance program for first-time buyers. My first-time buyer programs guide covers it.
Frequently asked questions
How long does the whole process take?
Usually 30 to 45 days from an accepted offer to closing. Shopping can take as long as you need.
Can I buy with less than 20% down?
Yes. Three to 5% down is common, and VA and USDA loans allow zero down for eligible buyers.
Will my property taxes be the same as the seller's?
Usually not. Expect a reassessment and plan for a higher bill after your first January 1, unless the seller bought recently.
What about new construction?
Most of these steps still apply, but builder contracts, deposits and incentives work differently. Start with my new construction guide, and bring me to your first visit with the builder.
Do I need a survey?
Your lender may not require one, but I recommend it. It confirms the lot lines, fences and any encroachments before you own the problem.
Ready to start?
The best first step is a 30-minute conversation about your budget, timeline and must-haves. Call or text me at (386) 627-3612, or book a buyer consultation and I'll map out your search and the Florida-specific costs for the homes you like.
New articles by email
Get my new articles every Saturday
One short email a week with what I posted: Palm Coast news, local events, community guides and the market. No new articles, no email.
About the Author
David Stanley is a Broker Associate with CENTURY 21 Fine Homes & Estates Realty Exchange and has lived in North Florida for 23 years. A former Flagler Beach Ocean Rescue lifeguard and firefighter, he has closed over $60 million in Palm Coast-area sales.
More about David · Pick a time to talk